Malay

- Produk

Adakah bursa kripto anda bersedia untuk 2026?
Lihat MaklumatBursa Aset Digital CEX Dilancar dalam 7 hari dengan sistem dagangan tahap perusahaanDompet Kripto MPC + storan sejuk untuk perlindungan aset menyeluruhKecairan Agregasi kecairan global dengan spread rendahBursa Desentralisasi DEX Dagangan desentralisasi rentas rantaian tanpa kustodiPlatform Dagangan NFT Pelancaran satu klik untuk dagangan NFT pelbagai modPertumbuhan Pengguna Alat pemerolehan dan pengekalan pengguna bersepaduPasaran Ramalan NewSeni bina multi-oracle dengan penyelesaian automatik on-chainRWA Tokenisasi aset dunia sebenar secara patuh - Penyelesaian
- Blog
- Tentang Kami


Institutional Block Trading & OTC Desk for SEA Crypto Platforms
Abstract
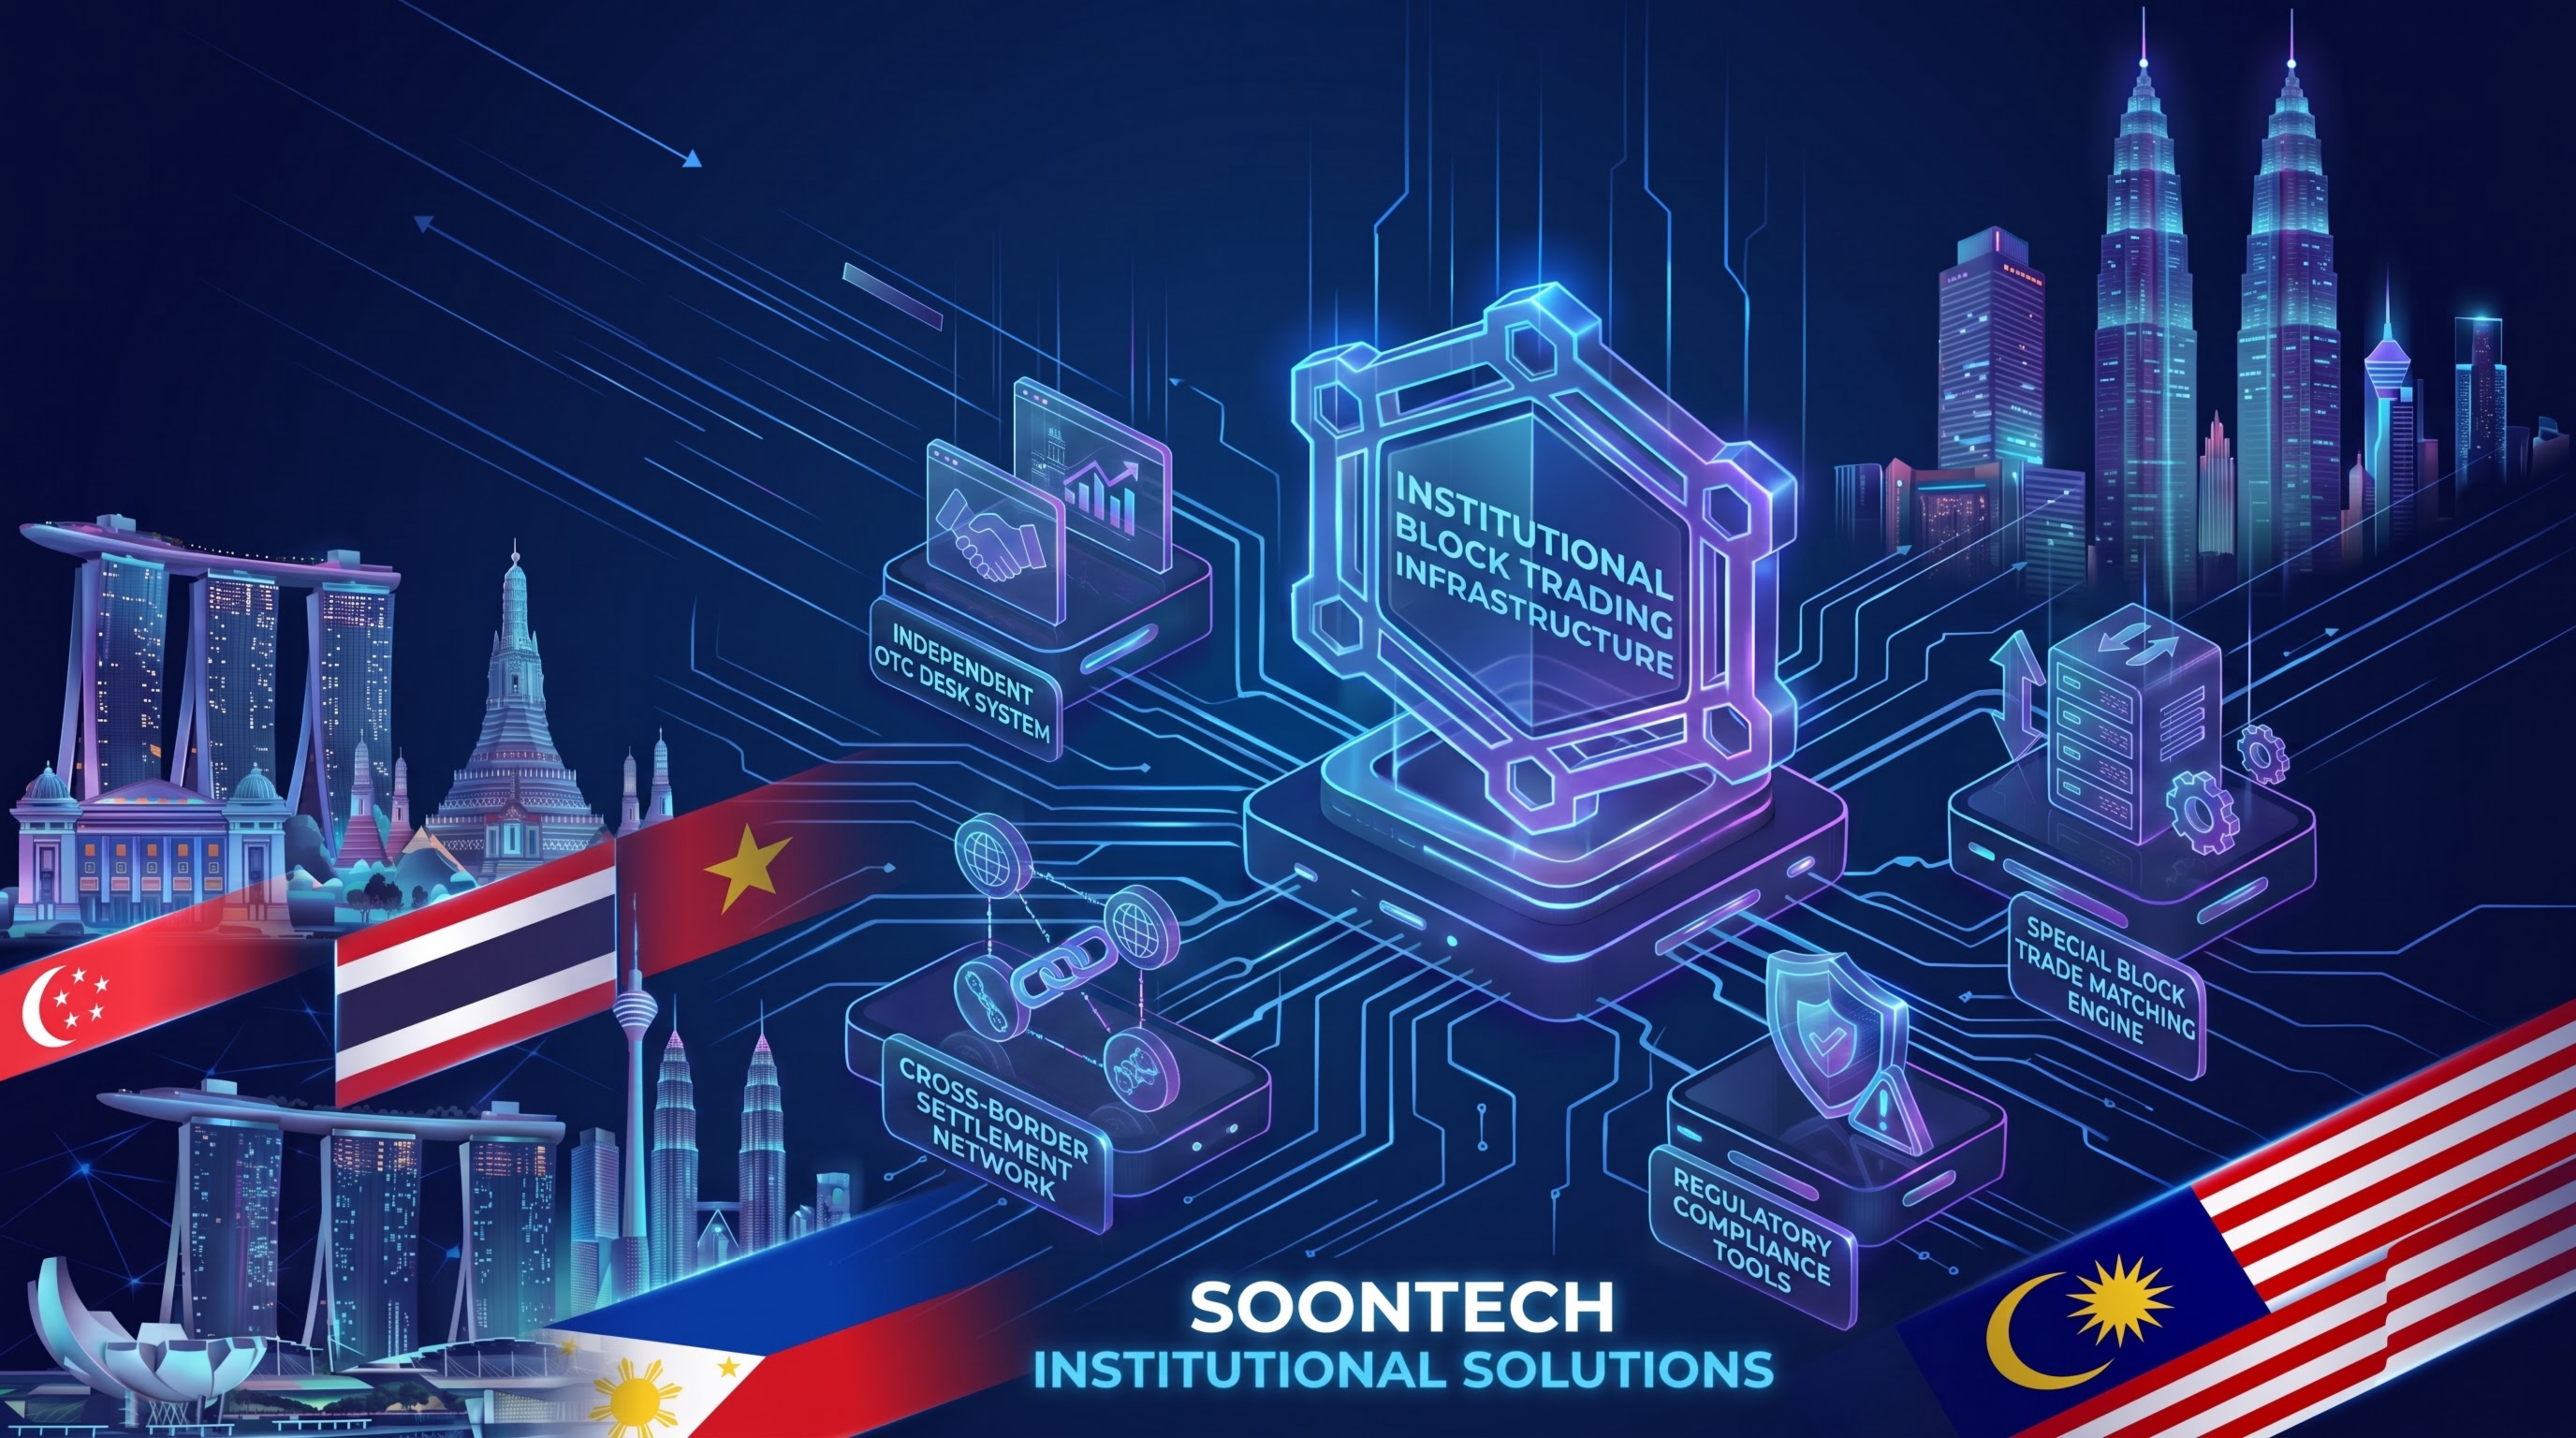
Institutional funds including family offices, asset management companies and private investment institutions in Southeast Asia have growing demand for large‑volume low‑slippage block trading and off‑exchange OTC transactions. Ordinary retail spot trading systems cannot meet the personalized quotation, fund risk isolation and cross‑border settlement needs of institutional clients. SoonTech launches exclusive institutional block trading infrastructure, integrating independent OTC desk system, block trade matching engine and multi‑jurisdiction cross‑border stablecoin settlement network. This article sorts out the differentiated service demands of Southeast Asian institutional users, introduces the core functional modules of institutional trading infrastructure, and expounds the compliant one‑stop service path for platforms to develop institutional business.
1. Differentiated Demand Characteristics of Southeast Asian Institutional Investors
- Large single transaction volume: Institutional orders often reach millions of US dollars; ordinary spot order books will cause severe market impact and asset price fluctuations;
- Demand for private OTC quotation: Institutions hope to complete off‑exchange negotiated transactions without affecting public market prices;
- Strict asset risk isolation: Institutional funds need independent sub‑account management, separated from retail user assets;
- Cross‑border asset allocation demand: Frequently carry out cross‑country digital asset transfer and settlement between Malaysia, Singapore, Vietnam and other regions;
- Complete compliance data records: Institutional transactions require standardized audit documents to meet local regulatory VASP reporting obligations.
2. Three Core Components of SoonTech Institutional Block Trading Infrastructure
2.1 Independent Institutional OTC Desk System
Separate background management and trading front‑end exclusive for institutional clients. Support bilateral negotiated quotation, custom transaction price and settlement cycle. Record all off‑exchange negotiation records, transaction contracts and fund transfer logs to form complete institutional compliance files. Platform operators can set OTC transaction risk limits, control the maximum single transaction amount and institutional client access qualification.
2.2 Special Block Trade Matching Engine
Independent high‑concurrency matching engine isolated from retail spot trading system, dedicated to large‑volume block order matching. The system adopts hidden order logic to avoid exposing institutional buying/selling intentions to the public market, effectively eliminating market price impact and slippage loss. Support spot, perpetual contract and RWA token block trading matching.
2.3 Cross‑Border Multi‑Jurisdiction Settlement Network
Connect stablecoin cross‑chain transfer channels and local fiat payment gateways of multiple Southeast Asian countries. After institutional block transactions are completed, the system supports automatic cross‑border stablecoin settlement or direct exchange into local legal tender. All cross‑border transfer data complies with FATF Travel Rule standards and can be exported for regulatory filing.
3. Institutional Exclusive Supporting Function Modules
- Independent institutional asset sub‑account: Separate storage of institutional client assets, isolated from retail user funds, meeting SC, MAS asset segregation audit standards;
- Institutional KYC dedicated channel: Rapid review process for enterprise institutional identity materials, supporting long‑term cooperation qualification filing;
- Customized transaction report: Automatically generate institutional asset allocation, transaction volume and settlement statements for internal financial accounting and regulatory reporting;
- MPC multi‑signature institutional fund approval: Large‑volume cross‑border settlement orders require multi‑level financial approval to avoid misoperation of institutional assets.
4. Landing Case: Singapore Family Office Institutional Trading Cooperation
Project Background
A Singapore licensed exchange intended to attract local family office and asset management institutional clients, lacking independent OTC and block trading modules. The platform deployed SoonTech institutional trading infrastructure in Q1 2026.
Implementation Results
- Launched independent OTC negotiation desk and hidden block matching engine, attracted 8 local family offices within two months;
- Institutional sub-account system realized full asset isolation, passed MAS compliance inspection;
- Cross-border settlement network supported SGD, MYR multi-region asset allocation for institutions;
- Custom institutional transaction reports reduced finance sorting workload by over 85%;
- Institutional trading revenue accounted for 36% of total platform income after 3 months.
5. FAQ
Q1: What’s the difference between block trade engine and retail spot matching engine? A: Block engine uses hidden orders to avoid market price impact, independent from retail order book, specially designed for million-dollar large institutional orders.
Q2: Can institutional client assets be separated from retail user funds? A: The system provides exclusive institutional sub-account ledger, completely isolated from retail assets, satisfying regional regulatory asset segregation rules.
Q3: Does the OTC system generate complete compliance documents for regulatory filing? A: All negotiation records, transaction contracts and settlement logs are permanently stored, supporting one-click export of institutional audit reports.
Q4: Can institutions conduct cross-border settlement between Malaysia, Singapore and Vietnam through the system? A: Yes, multi-jurisdiction settlement network connects cross-chain stablecoin channels and local fiat gateways for regional asset allocation.
6. Business Value for Southeast Asian Digital Asset Platforms
- Capture high‑margin institutional transaction revenue: Block trading and OTC businesses have higher handling fee rates than retail spot transactions, forming differentiated profit sources;
- Form platform competitive barriers: Most small local exchanges only support retail trading; complete institutional infrastructure can attract exclusive cooperation with family offices and asset management institutions;
- Expand cross‑border business coverage: The multi‑country settlement network supports institutions to carry out regional asset allocation, expanding platform user boundary;
- Meet regulatory institutional service compliance requirements: Complete transaction traceability and asset isolation modules help platforms pass periodic regulatory inspections smoothly.
7. Conclusion
Institutional block trading and OTC off‑exchange business is the core high‑growth track of Southeast Asia’s digital asset market in 2026. Retail‑oriented ordinary exchange systems lack professional institutional trading and settlement capabilities, limiting platforms to capture institutional incremental capital. SoonTech’s integrated institutional block trading infrastructure integrates OTC negotiated transactions, hidden large‑order matching engine and cross‑border settlement network, equipped with exclusive institutional asset management and compliance tools. It helps licensed exchanges and regional brokers in Southeast Asia quickly deploy institutional business, build differentiated competitiveness and obtain stable high‑value institutional trading revenue.